
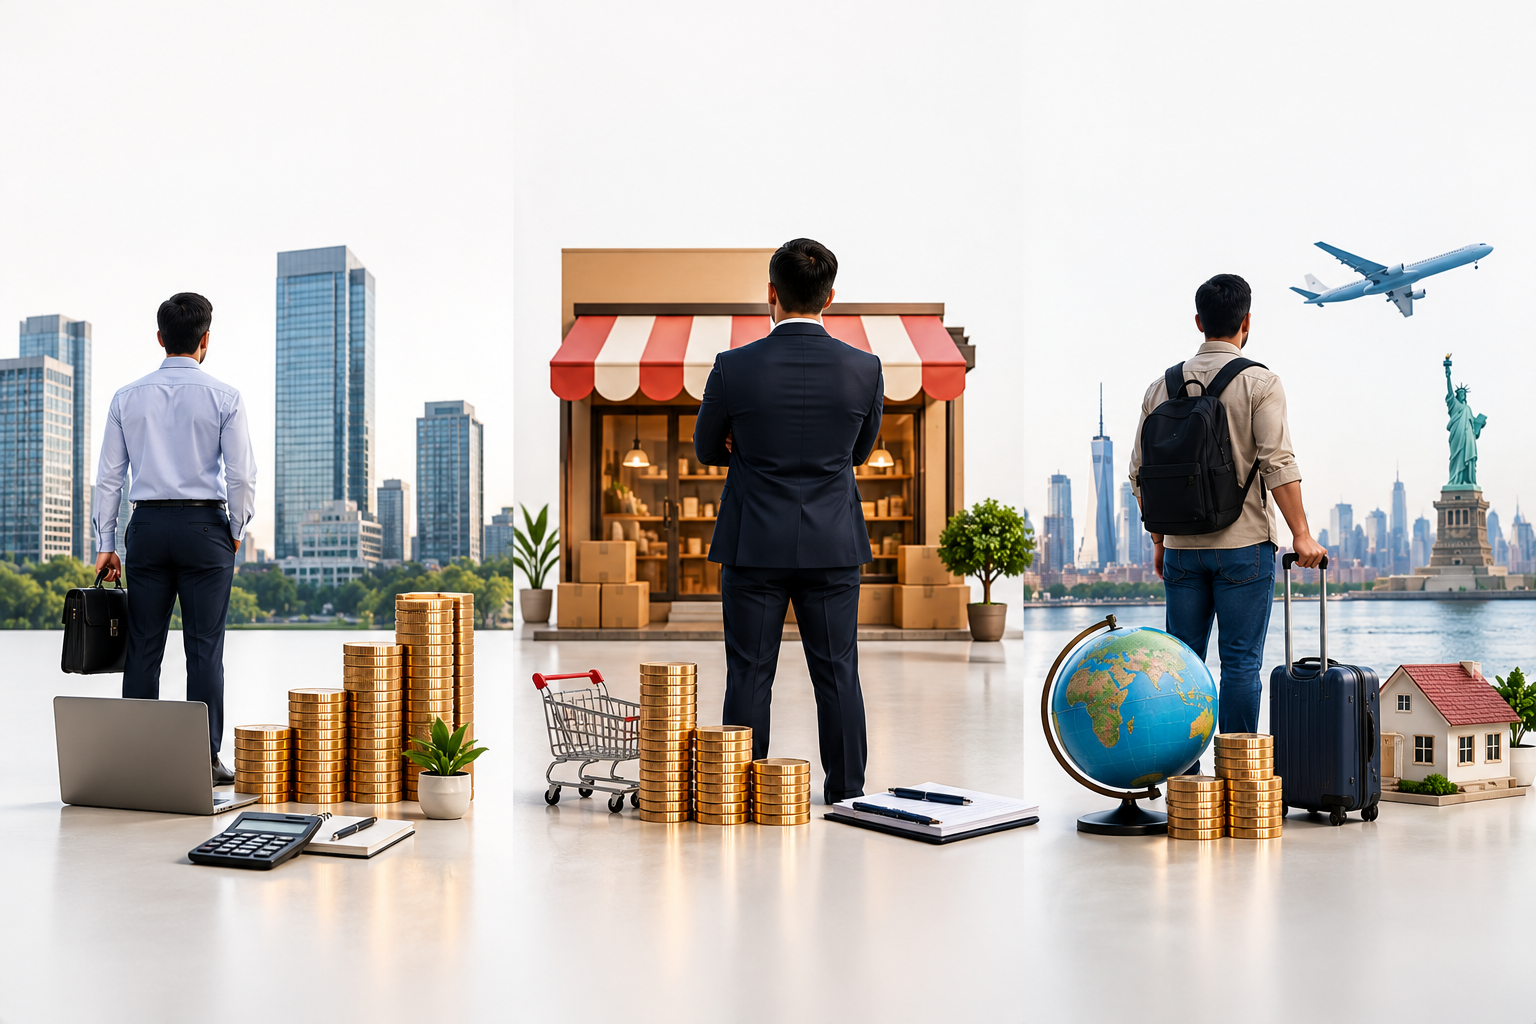
Two people can earn the same ₹30 Lakh a year and need completely different Financial planing strategies. One has a monthly salary, EPF and an employer health cover. Another has a business whose income swings between quarters and whose biggest asset is the business itself. A third lives in Dubai, earns in Dirhams, and has parents, property and investments back in India.
Financial planning for salaried professionals, business owners and NRIs follows the same basic steps: protect, save, invest and plan for retirement. What changes is how much liquidity you need, which risks matter most, how you are taxed, and which rules apply to your money. This guide covers each group and ends with a comparison table you can use as a checklist.
In this guide
- Why the three plans differ
- Financial planning for salaried professionals
- Financial planning for business owners
- Financial planning for NRIs
- Comparison table
- Common mistakes
- How to start in five steps
- FAQs
This article is educational and not personalized financial or tax advice. Tax rules change often. Confirm current figures with the Income Tax Department or a qualified professional before acting.
Why one financial plan doesn’t fit everyone
A plan depends on four things: how stable your income is, who depends on it, how your income is taxed, and which regulations govern your money. A salaried employee mostly has stable income and automatic savings through payroll. A business owner has variable income and mixes personal and business risk. An NRI has to deal with cross-border tax and foreign exchange rules on top of everything else.
Financial planning for salaried professionals
What makes the salaried situation different
Your income is predictable and your tax is deducted at source, which makes planning easier. The risk is that things feel handled when they aren’t. Employer cover usually ends when the job does, and EPF alone rarely funds a full retirement.
1. Choose your tax regime deliberately
The Income-tax Act, 2025 came into force on 1 April 2026 and replaces the 1961 law. Budget 2026-27 made no change to income tax slabs. The ₹75,000 standard deduction for salaried people under the new regime also continues for Tax Year 2026-27. The new regime is the default regime.
The practical rule is to calculate both regimes each year rather than assuming one wins. The old regime can still come out ahead if you have significant deductions such as home loan interest, HRA and eligible investments. Use the official Income Tax Department calculator for your numbers.
2. Build an emergency fund first
A common guideline is 6 months of essential expenses in a liquid, low-risk place such as a savings account, liquid fund or short-term deposit. People with a single income earner in the family or an uncertain industry often hold more. This is a rule of thumb, not a regulation.
3. Fix insurance before investing aggressively
- Term life insurance: needed if anyone depends on your income. A frequently quoted range is 10 to 15 times annual income, but the right number depends on loans, dependents and existing assets.
- Health insurance: buy a personal policy even if your employer provides one. Group cover can disappear when you change jobs or retire.
4. Use retirement tools you already have
- EPF and VPF: a steady, low-risk base.
- NPS: an employer contribution to NPS has been allowed as a deduction under the new regime as well. Check the current limit with your payroll or tax professional.
- SIPs in diversified equity and index funds: for long-term growth that EPF alone won’t deliver.
5. Handle ESOPs and bonuses carefully
Employee stock options are taxed at exercise as a perquisite and again at sale as capital gains. Plan the cash for the first tax bill before you exercise.
Financial planning for business owners
What makes this situation different
Your income is irregular, your wealth is concentrated in one business, and the business and your family finances are often tangled together. Most business-owner plans fail for one reason: personal and business money share an account.
1. Separate business and personal finances
Pay yourself a defined salary or drawing from the business account into a personal account. This makes your personal budget realistic, simplifies tax filing, and makes it easier to get loans and insurance.
2. Keep a larger emergency reserve
Business income can fall suddenly. Many planners suggest 9 to 12 months of personal expenses plus a separate working-capital buffer for the business. Keep the two reserves separate.
3. Understand your tax structure
Tax depends on whether you operate as a proprietor, partnership, LLP or company. Small businesses and professionals may qualify for presumptive taxation under Sections 44AD and 44ADA, which have turnover limits that have been revised over time. A chartered accountant should confirm your eligibility. A company can also choose between salary and dividend, and the tax effect of each should be compared.
4. Cover business-linked risks
- Term insurance large enough to cover business loans you have personally guaranteed.
- Health insurance for you and your family, since there is no employer cover.
- Key-person and business continuity planning if the business depends on you or a partner.
5. Don’t make the business your entire retirement plan
Many owners assume they will sell the business to fund retirement. That depends on a buyer and a valuation you can’t guarantee. Build an independent corpus through NPS, mutual funds and other diversified assets, so retirement doesn’t depend on a sale.
6. Plan succession early
A will, nominee details and a clear plan for who runs the business protect the family and the company.
Financial planning for NRIs
What makes this situation different
NRIs deal with two countries’ rules. The main concerns are residential status, the right bank accounts, which investments are permitted, how Indian income is taxed, and how money moves back abroad.
1. Confirm your residential status each year
Under Indian tax law, your status as resident or non-resident is determined by days spent in India in the year and preceding years. Rules differ for Indian citizens who leave India for employment and for those who visit. Status can change, and it affects how your global income is taxed, so verify it every year.
2. Use the right bank account
| Account | Holds | Interest tax in India | Repatriation |
| NRE | Foreign earnings | Generally tax-free while you remain a non-resident | Freely repatriable |
| NRO | Indian income (rent, dividends, etc.) | Taxable, with TDS | Limited per year, subject to conditions |
| FCNR | Foreign currency deposits | Generally tax-free for non-residents | Repatriable |
Check current RBI and bank rules before opening or converting accounts, as limits and conditions can change.
3. Know where you can and can’t invest
NRIs can invest in Indian mutual funds, listed equities (through an authorized route such as a PIS account), NPS and certain deposits. Some restrictions apply: agricultural land, plantation property and farmhouses cannot be bought by NRIs, and some fund houses restrict investors from particular countries. Confirm availability with the platform before planning around a product.
4. Understand Indian taxes on your income
- Indian-source income such as rent, interest, dividends and capital gains is taxable in India.
- TDS on NRI income is often higher than for residents, especially on property sales and NRO interest.
- A Double Taxation Avoidance Agreement (DTAA) between India and your country of residence may allow you to claim credit or relief, so you are not taxed twice on the same income.
5. Plan repatriation and currency risk
Your goals may be in rupees (a home or family support in India) or in your country of residence. Decide which, because currency movements can change returns significantly when converted back.
6. Don’t forget the Indian side of family planning
NRIs often have parents in India, jointly held property and nominations that are outdated. A power of attorney, a valid will and updated nominees avoid long delays later.
Comparison: Salaried vs Business Owner vs NRI
| Area | Salaried | Business owner | NRI |
| Income | Stable, monthly | Variable | Often foreign currency |
| Emergency fund | ~6 months | ~9 to 12 months plus business buffer | Depends on where expenses fall |
| Tax handling | TDS, regime choice | Structure-based, advance tax | Residential status, TDS, DTAA |
| Insurance gap | Losing employer cover | No employer cover, business debt | Cover in India vs abroad |
| Retirement tools | EPF, VPF, NPS, SIPs | NPS, mutual funds, non-business assets | NPS, mutual funds, deposits |
| Biggest risk | Under-saving | Concentration in one business | Compliance and currency |
| First action | Compare tax regimes | Separate finances | Confirm residential status |
Common mistakes by group
Salaried: relying only on employer insurance, ignoring the EPF-only retirement shortfall, and never reviewing the tax regime.
Business owners: mixing accounts, having no personal emergency fund, and treating the business as the retirement plan.
NRIs: keeping money in the wrong account type, missing Indian tax filings, and not updating nominees and wills.
How to start in five steps
- Write down income, expenses and dependents to understand your cash flow.
- Build the emergency fund appropriate to your group.
- Close the insurance gap with term and health cover.
- Set goals with dates and amounts: retirement, children’s education, a home.
- Invest through suitable products and review once a year or after major life changes.
Frequently Asked Questions
What is the difference between financial planning for salaried people and business owners?
Salaried people have stable income and automatic savings, so planning focuses on tax choices, insurance, and retirement. Business owners have variable income and concentrated risk, so planning focuses on separating finances, maintaining larger reserves, and non-business retirement assets.
What financial planning does an NRI need in India?
An NRI needs to confirm residential status, use NRE, NRO and FCNR accounts correctly, understand Indian tax and TDS, check DTAA relief, and plan repatriation of funds.
Is the new tax regime better for salaried employees?
It depends on your deductions. The new regime is the default, but the old regime can be better if you claim substantial deductions. Calculate both every year.
How big should a business owner’s emergency fund be?
Many planners suggest 9 to 12 months of personal expenses, plus a separate working-capital reserve for the business.
Can NRIs invest in mutual funds in India?
Yes, generally, subject to KYC and FATCA compliance. Some fund houses limit investors from certain countries, so check with the fund house.
Does an NRI pay tax in India and abroad on the same income?
Possibly, but a DTAA between India and the other country may provide credit or relief to avoid double taxation. Seek professional advice for your situation.
How often should I review my financial plan?
At least once a year, and after major events such as a job change, business expansion, marriage, a child’s birth, or a move abroad.
Conclusion
The three groups share the same goals but face different risks. Salaried professionals should avoid complacency about employer benefits. Business owners should keep the business and family finances apart and build wealth outside the company. NRIs should get the account structure, tax status and repatriation rules right first.
If you’d like a plan matched to your situation, speak to a Wealth Forest advisor for a personalized review.